Donors ask this for two reasons: they want to know the airplane is not going to sit in a field, and their accountant needs to know whether the deduction rests on a sale price or an appraised value. Both answers come from the same decision, made early — what the aircraft is genuinely good for. This page walks the four destinations and what each one means on your Form 1098-C.
How the decision gets made
Within days of the first call we know most of what matters: the registry record, the maintenance status, whether it can fly, and what the type is worth in the condition described. The destination follows from that rather than from preference.
- Can it be made airworthy for a sensible cost, and is the type in demand?
- Are the records complete enough for a buyer, or only for a teaching airframe?
- Does a school or program have a current need for this type?
- Do the components — panel, engine, gear, interior — carry more value separately?
We tell donors the likely answer before anything is signed, because it changes the tax treatment and nobody should learn that afterwards.
Sold to fly again
The most common outcome for sound aircraft. It goes to a buyer through the usual channels, and the price it brings becomes your deduction: gross proceeds, reported on Form 1098-C within 30 days of the sale.
Buyers are mostly ordinary owners and operators — a partnership looking for a first airplane, a school adding a trainer, a rebuilder who does this for a living. Where a lapsed annual or an expired database stands in the way, the buyer usually handles it, which is precisely why they are the buyer and you were not.
Retained for a charitable use
Where an airframe is worth more as a teaching platform than as an aircraft, it goes to a program that will use it. Maintenance schools are the largest recipients: an A&P program can teach sheet metal, riveting, systems, engine work and inspection on a complete airframe in a way no mock-up allows, and schools rarely have enough of them.
- A&P and technical programs. Complete airframes for disassembly, inspection and repair instruction.
- Youth aviation and STEM programs. Ground-school airframes, build projects and career-day equipment.
- Builders’ associations and chapters. Chapter projects that put a stalled airframe in front of people who want to learn on it.
- Occasional operational use. Rarely, an aircraft suits a charitable mission directly rather than a sale.
This is the case where we certify a significant intervening use and the deduction rests on appraised fair market value rather than proceeds. It is also the case that needs a qualified appraisal.
Parts recovery
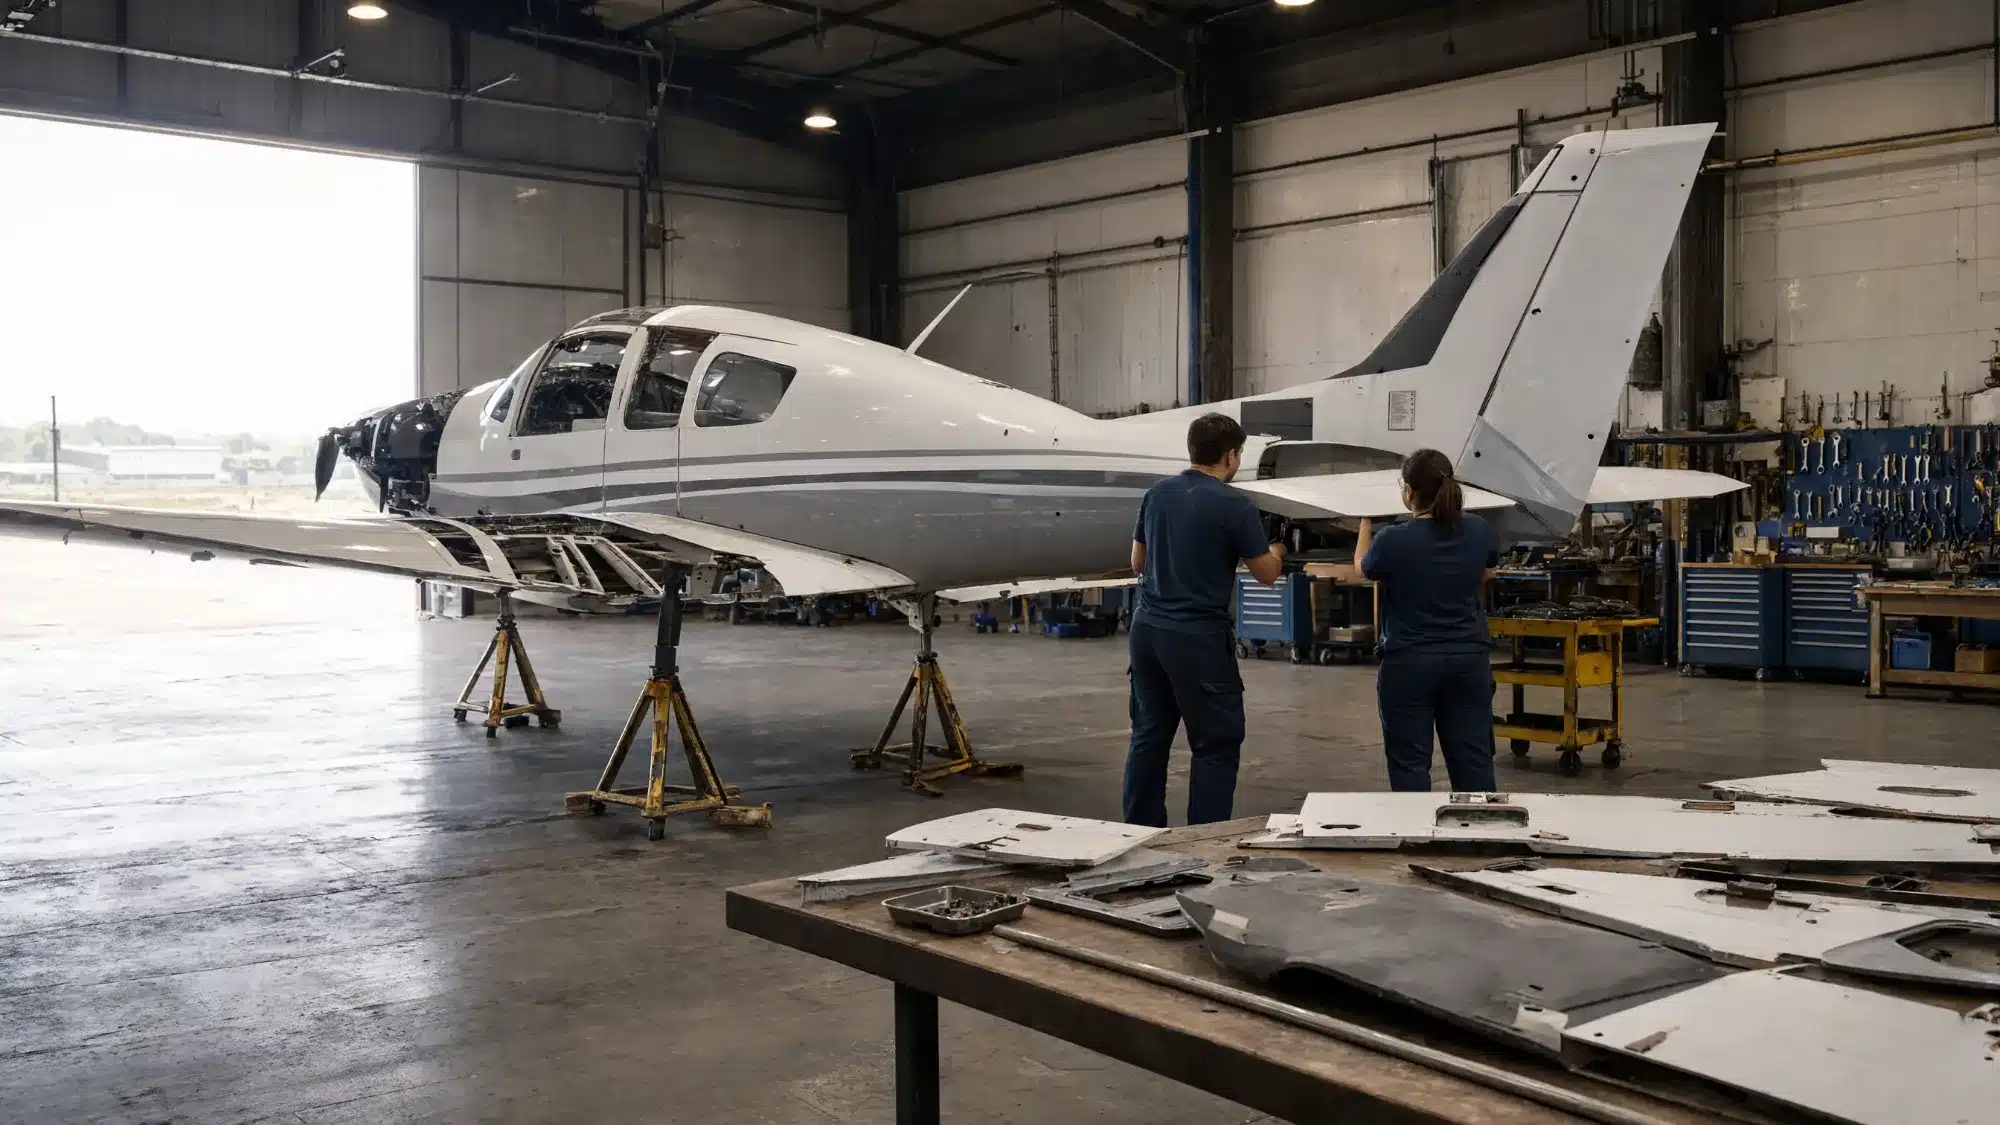
For a damaged or mandate-grounded airframe, the components frequently carry more value than the whole. The panel, a mid-time engine that did not suffer a sudden stoppage, control surfaces, gear components and interior all return to a supply chain that keeps other aircraft flying — which is a genuine use, not a euphemism for scrapping.
What remains after recovery is dismantled and recycled rather than left occupying somebody’s ramp. Where the airframe is dismantled rather than returned to service, deregistration may be part of the process, and we handle that filing. See damaged aircraft and parts and avionics.
How the destination shapes your deduction
This is the whole reason the destination matters to your accountant, and the mechanics are on the tax deduction page.
What you will be told, and when
- At the first call: the likely destination, and therefore the likely basis of your deduction.
- At signing: a written acknowledgement of the donation.
- On sale: Form 1098-C with the gross proceeds, within 30 days.
- On retention: our certification of the significant intervening use, for your Form 8283 file.
- On request: what happened to the aircraft. We will tell you where it went.
One caveat we state plainly: plans change. An airframe intended for a school occasionally proves airworthy enough to sell, and an aircraft listed for sale occasionally turns out to be exactly what a program needed. Your paperwork reflects what actually happened, not what was expected.


Destination drives the basis
Two bases, one determined by what the charity does with the aircraft. If we sell it, the donor’s deduction is generally limited to gross proceeds, reported on Form 1098-C within 30 days of sale. If we retain it and put it to a significant intervening use, we certify that use and the deduction rests on fair market value, which requires a qualified appraisal above $5,000.
Parts recovery is ordinarily a sale for these purposes: the components are sold and the proceeds are reported. Where the airframe is dismantled and deregistered, keep the deregistration documentation with the contribution file.
Because the destination is not always known at the contribution date, expect the 1098-C to arrive after the transfer — frequently in the following calendar year for a late-December gift. That timing does not move the contribution date, which is set by title transfer and delivery.
Authority: IRS Publication 526 on charitable contributions, Publication 561 on valuation, plus the Form 1098-C and Form 8283 instructions. Nothing here is tax advice — confirm the figures with your own CPA. How the deduction works →
Related reading
Ask where yours would go
Tell us the type and condition and we will tell you the likely destination, and what that means for your paperwork.