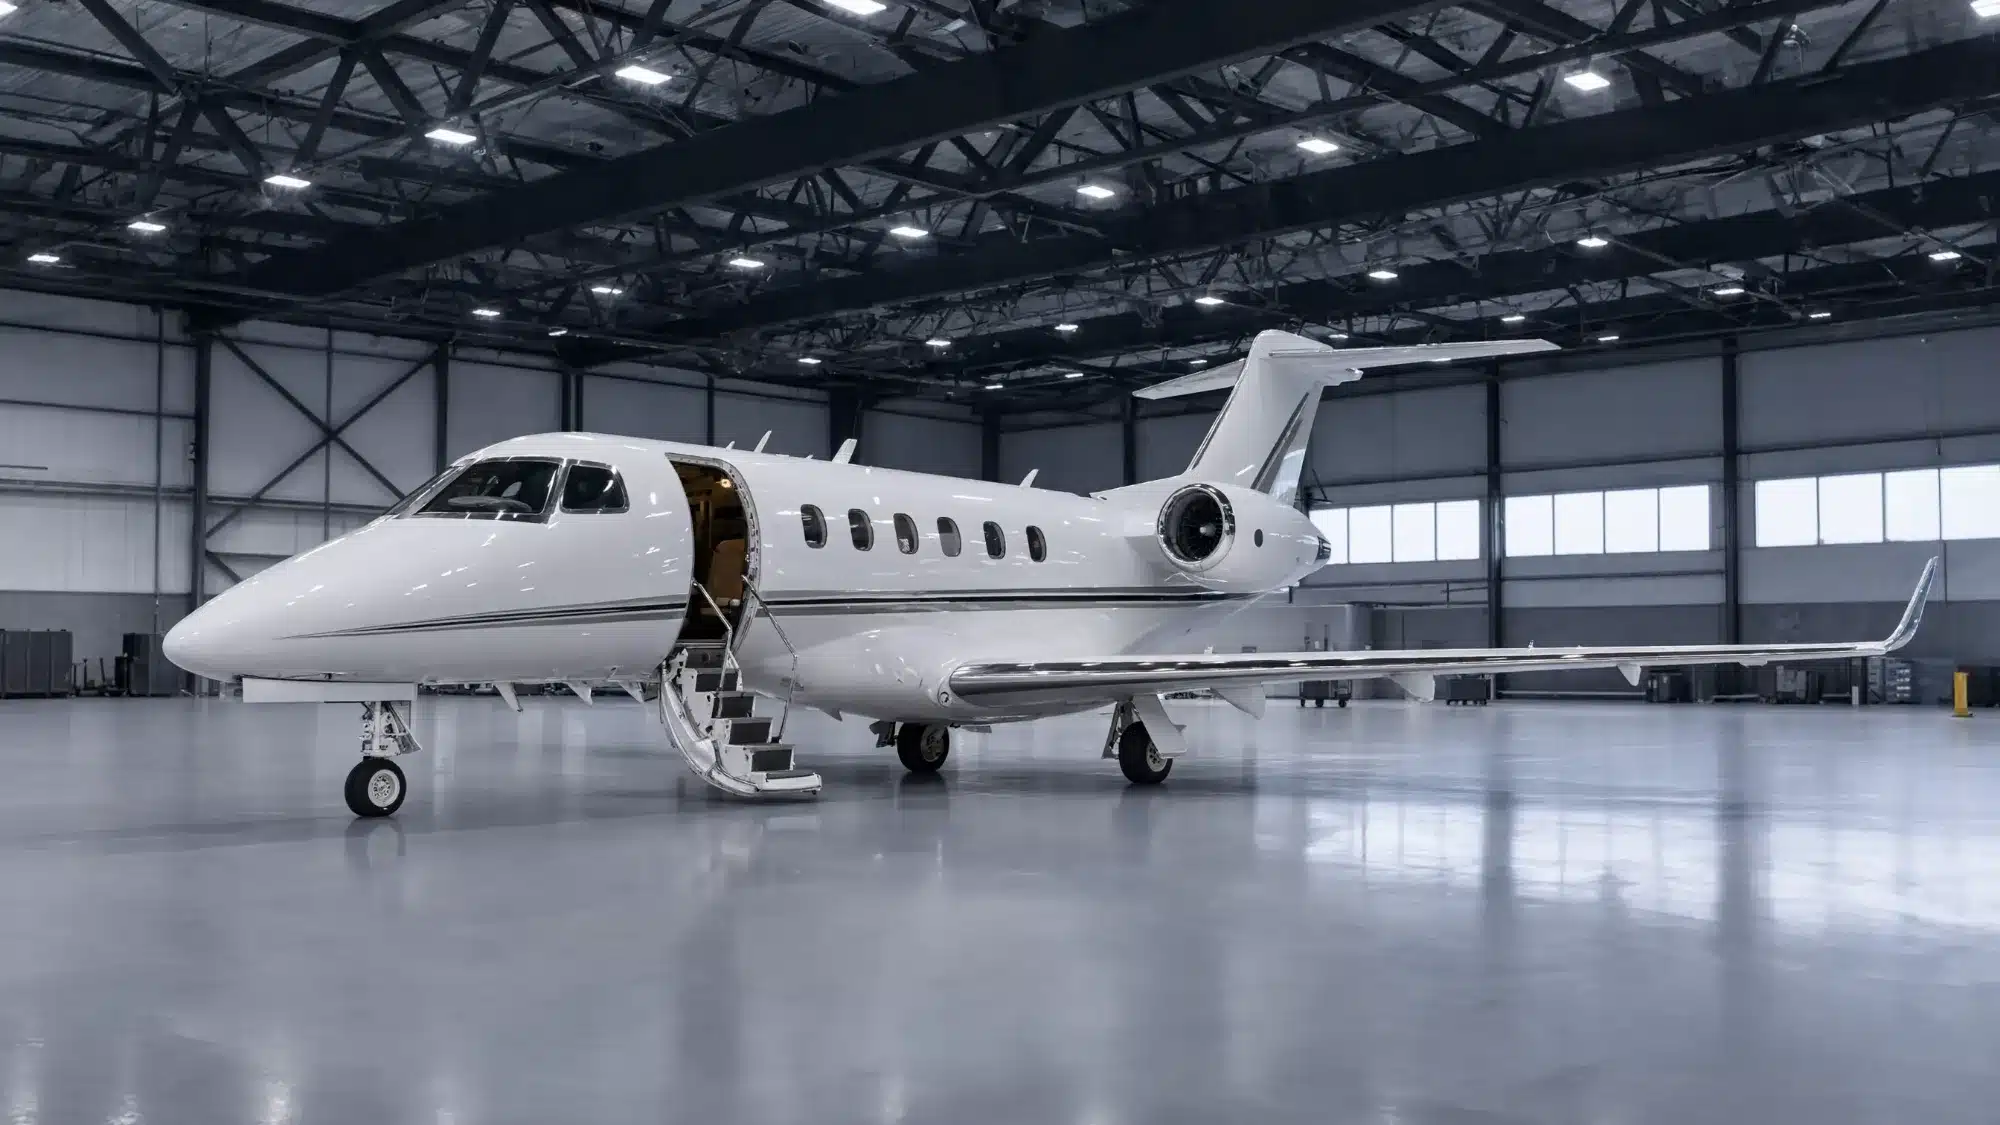
Phenoms are newer than most of what we take, and they arrive for different reasons: an owner-operator whose medical or circumstances changed, a charter operation that restructured, an estate holding an aircraft with an active maintenance commitment. Because the fleet is young, mandate exposure is rarely the issue — program enrollment and records continuity are. A Phenom that has been maintained in program and flown regularly is a straightforward sale; one that has lapsed and sat is a more involved conversation, and both are welcome.
What moves the number on a Phenom
Program enrollment and continuity. Whether the aircraft has been maintained under its support programs without interruption is the dominant factor here — more so than on older jets. A lapse does not disqualify the aircraft, but it changes the buyer pool and the figure, and we would rather establish it on the first call.
Engine and airframe status. Time and cycles against inspection intervals, plus any deferred items. Modern aircraft accumulate deferrals quickly once flying stops, and those are ordinary to us.
Avionics currency. Integrated glass panels need database and software currency, which lapses on a parked aircraft. Cheap to resolve relative to the airframe, but a buyer will price it, so we ask.
Records continuity. Digital and paper records both matter, and continuity across ownership changes is what a buyer's technical review looks for. Send what exists; we reconstruct from status pages regularly.
How a Phenom gets to us
Airworthy aircraft are flown out by a type-rated crew under our insurance. Where an aircraft has been parked long enough to need inspection before flight, we arrange that work first rather than moving it on assumptions. Hangar, insurance and program costs accrue until the aircraft is gone, so the schedule is built backwards from your billing dates, and any lien, lease or fractional interest is resolved before the aircraft moves.
What the first call covers


What you can deduct for this aircraft
Phenoms almost always sell rather than being retained or dismantled, so your deduction is the gross proceeds reported on Form 1098-C. Program status is the variable that matters most: an in-program aircraft sells for materially more than a lapsed one, and since the deduction follows the sale, that difference lands directly in your claim. It is the one case where resolving a lapse before donating can be worth discussing.
A qualified appraisal and Form 8283 Section B apply at this value, and corporate ownership with depreciation should be reviewed by your CPA before you assume a figure.
Rules for aircraft gifts are in IRS Publication 526, valuation in Publication 561. Nothing here is tax advice — confirm your figures with your CPA. How the deduction works · FAA paperwork
Other models in this class
Start with the N-number
We will pull the registry record before we call you back.